Dropside cover
Dropside lorry insurance for open loads and site deliveries
Rigids with fold-down sides carrying materials, scaffold or plant. A single short form leads to specialist dropside brokers.
- With or without crane or tail lift
- Own goods or haulage
- One dropside or several
Quick answer
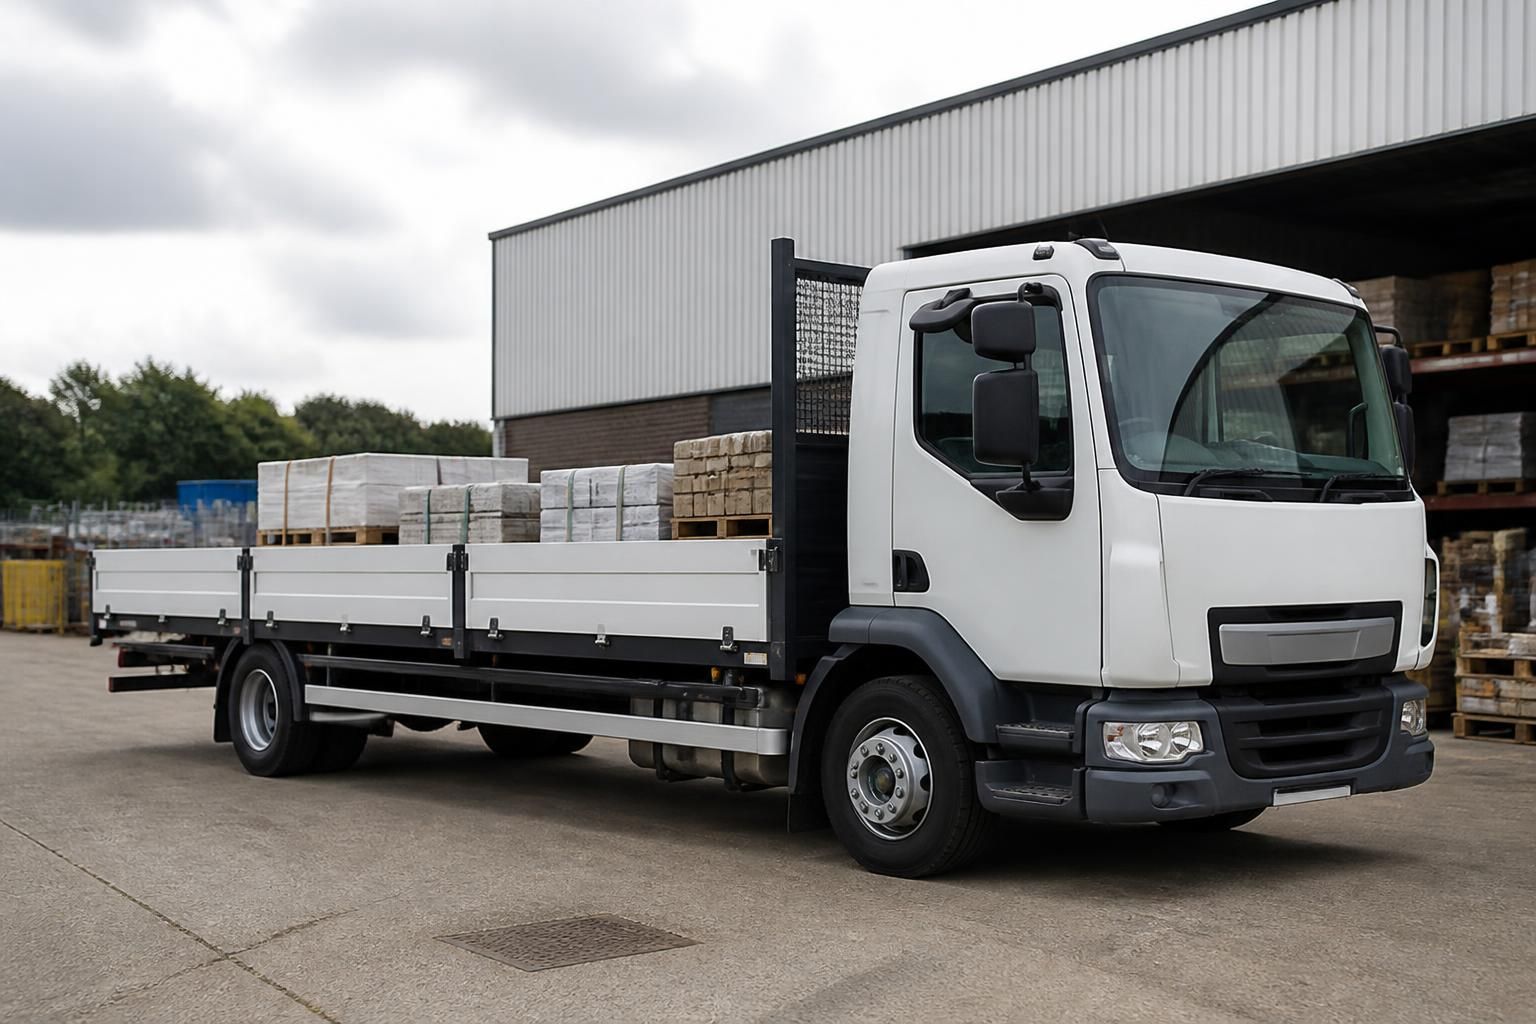
Dropside lorry insurance is motor cover for a rigid goods vehicle with a flat open body whose side boards and tailboard are hinged, so they fold down for loading. Insurers rate it on what goes on the bed, how that load is held in place, any crane or tail lift fitted, and whether you carry your own materials or other people's goods for payment.
Dropside cover at a glance
- The body is open to the weather and to theft, so how loads are secured and stored overnight matters to insurers.
- A crane or tail lift brings a loading risk on top of the driving risk, and insurers usually ask about both.
- Merchants, scaffolders, landscapers and councils mostly carry their own materials, which insurers rate differently from haulage.
- Running heavy is a real issue on a dropside, because dense loads such as blocks or aggregate reach the weight limit before the bed looks full.
- Most goods vehicles over 3.5 tonnes gross weight used for business need an operator licence, and brokers will ask which type you hold.
What dropside lorry insurance covers
A dropside policy is built around the lorry itself, with extra sections for the kit fitted to it and the materials on the back. How far each section reaches varies between insurers.
Dropside lorry types and what insurers look at
The same open body appears on very different chassis, and the equipment bolted to it shifts the risk more than the bodywork does.
| Dropside type | Typical work | What insurers look at |
|---|---|---|
| 7.5 tonne dropside | Local deliveries for merchants, councils and small building firms | Driver licence category, payload margin, town-centre parking |
| Dropside with a tail lift | Palletised goods, tools and small plant dropped at kerbside | Lift condition, manual handling, goods dropped while lowering |
| Dropside with a loader crane | Bricks, blocks, timber and bulk bags placed onto site | Crane value and use, operator training, lifts over third parties |
| Scaffold body dropside | Tube, fittings and boards between yard and site | Long loads, overhang, theft of tube and boards left on board |
A dropside that also tips is often treated as a tipper, as on our tipper lorry insurance page. For platform bodies with no side boards, flatbed lorry insurance covers the differences.
Carrying your own materials or other people's goods
Many dropsides on UK roads run on a restricted basis, moving stock, scaffold or plant that belongs to the business. Once you carry goods for customers in return for payment, both the licence and the insurance change.
Own goods operators
A merchant delivering its own sand and timber, or a scaffolder moving its own tube, normally insures for carriage of own goods under a restricted licence, as set out on our own goods HGV insurance page.
Hire and reward
Carrying building materials or plant for other firms, or renting the lorry out with a driver, needs a standard licence and haulage use, as covered on our haulier insurance page.
Which class of use fits a dropside carrying customers' materials for a fee?
- NoSocial, domestic and pleasureDoes not extend to any business deliveries.
- NoCarriage of own goodsFine for your own stock and kit, not for paid loads.
- YesHaulage, or hire and rewardOther people's goods carried in return for payment.
Licence and weight points
Most goods vehicles over 3.5 tonnes gross weight used for business need an operator licence, and loads are expected to be secure and within the vehicle's plated weights. A prohibition for overloading or an insecure load can count against you at renewal, so brokers may ask about roadside checks when you begin a dropside quote (opens in a new tab).
What affects the price of dropside lorry insurance
Price reflects the chassis, the driver and the work, but an open body brings extra themes: what can be stolen off the back and what can fall off it.
On the move
Unsheeted loose materials, long scaffold tube hanging past the tailboard and loads near the weight limit raise the chance of a claim.
Parked up
Tools, plant and materials sitting on an open bed overnight are easy pickings, so secure yards and locked storage help.
- Gross weightA 7.5 tonne dropside and a large rigid sit in different rating bands with different driver pools.
- Fitted equipmentA crane or tail lift raises the vehicle value and adds a loading risk to price.
- Kind of loadBagged aggregate, scaffold tube, turf, small plant and glass are each viewed differently.
- Load security habitsStraps, nets and sheets in regular use show that loads are restrained between jobs.
- DriversAge, experience on rigids and recent convictions apply to each named or permitted driver.
- Several vehiclesMixed dropsides, vans and tippers can sit on one policy through HGV fleet insurance.
Cover that often sits alongside dropside insurance
A dropside policy concentrates on the vehicle. These covers pick up the people, materials and premises around it.
Before you buy
Points worth checking on a dropside policy
Open bodies, mixed loads and fitted kit leave room for gaps. These are the points brokers tend to go through before cover starts.
- Is the crane or tail lift covered while in use?Some motor policies exclude injury or damage caused while the crane or tail lift is working, leaving that to liability cover.
- Is theft from an open body covered?Goods left on an unsheeted bed overnight may face conditions or exclusions.
- Are your own materials insured on the bed?A motor policy rarely pays for stock lost or damaged in transit.
- Does cover hold if the lorry is found overweight?Insurers can treat an overloaded vehicle differently after an incident.
- Are long or overhanging loads accepted?Scaffold tube and timber beyond the tailboard may need to be declared.
- Who is allowed to drive?Named drivers, minimum ages and licence categories differ between insurers.
- Does the class of use fit every job?Occasional paid loads for another firm can sit outside own goods cover.
- What happens if the lorry is off the road?A replacement dropside, especially one with a crane, can be hard to source quickly.
How it works
How to get a dropside lorry insurance quote
HGV Insure is an information site, not an insurer or a broker. We link you to MyMoneyComparison.com, a comparison service that can put dropside operators in touch with specialist brokers.
- 1
The quote form
Get my dropside quote takes you to our partner, MyMoneyComparison.com.
- 2
Your dropside and the work
The form asks about the lorry, its weight and body, your operator licence and who drives. The broker follows up on any crane, tail lift and the loads carried.
- 3
Options from a broker
A specialist broker comes back with options, subject to insurers' acceptance criteria. Nothing has to be bought.
FAQs
Dropside lorry insurance FAQs
What is a dropside lorry?
It is a rigid lorry with a flat load bed edged by low side boards and a tailboard on hinges. The boards fold down so a forklift can load from the side, then fold up to help keep the load on board.
Is a dropside insured differently from a flatbed?
The cover is similar, but insurers may ask about the side boards, any tail lift and how loads are restrained. A plain platform with no sides is covered on our flatbed lorry insurance page.
Does my dropside policy cover the tail lift?
The tail lift itself is usually insured as part of the vehicle. Injury or damage caused while it is lowering goods may fall to liability cover instead, depending on the policy.
Who covers materials that blow or fall off the back?
Damage to other road users from an object falling off the lorry is usually a motor policy claim. The lost materials themselves are a separate matter for goods cover, and an insecure load can affect how a claim is handled.
Do I need an operator licence for a dropside?
If the dropside is over 3.5 tonnes gross weight and used for business, an operator licence is normally needed, though some uses are exempt. A restricted licence is for carrying your own goods and a standard licence is for hire and reward.
Can a council or local authority insure its dropsides this way?
Councils often place their vehicles on a fleet arrangement that includes dropsides, tippers and vans, which our HGV fleet insurance page explains.
What licence does a driver need for a 7.5 tonne dropside?
A 7.5 tonne dropside generally needs category C1. Drivers who passed their car test before 1997 usually have C1 already, though insurers may still ask about lorry experience, and the entitlement has to be renewed separately later in life. Heavier dropsides need category C, and our 7.5 tonne lorry insurance page has more on the lighter end.
Can I carry a mini digger on a dropside?
Some dropsides carry small plant, but insurers may want to know how it is loaded and chained down. Larger machines usually go on a plant body or a low loader.
Is every dropside lorry an HGV?
No. Light dropsides up to 3.5 tonnes can be driven on a car licence, need no operator licence and are usually insured as commercial vehicles rather than lorries. Larger two-axle and eight-wheel dropsides, often with a crane, need category C and are rated as heavy goods vehicles.
Does HGV Insure sell dropside lorry insurance?
No. HGV Insure is an information site and an affiliate of MyMoneyComparison.com, which matches operators with specialist brokers. When you start a quote you continue to MyMoneyComparison.com, and we may be paid a small commission if you are matched with and speak to a broker.
Ready to get your dropside covered?
One form, specialist HGV brokers, no obligation.
Get my dropside quote (opens in a new tab)